



 Click it and Unblock the Notifications



Latest Updates
-
 Rashmika Mandanna To Play M.S. Subbulakshmi: First Look To Be Unveiled On Singer’s 110th Birth Anniversary
-
 Ganpati Visarjan 2026: The Complete Guide To Dates, Timings And Rituals
-
 Former Andhra Pradesh Deputy CM Alla Nani Passes Away At 56 After Cardiac Arrest In Visakhapatnam
-
 Kim Kardashian Awarded Symbolic 1 Euro in Compensation Over 2016 Paris Jewel Heist
-
 Balarama Jayanti 2026: The Story, Significance And Rituals Honouring Krishna’s Elder Brother
-
 Skanda Sashti September 2026: Significance, Tithi Timings, Vrat And Puja Rituals To Know
-
 International Day for the Preservation of the Ozone Layer: Date, History, Significance, and More
-
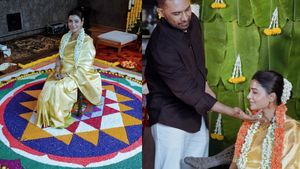 Samantha Ruth Prabhu's Baby Shower Look Has Fans Talking — Here's Why
-
 Exosomes vs PDRN: What Should Patients Know Before Choosing a Regenerative Skin Treatment?
-
 Adhi Vinayaka Temple: Tamil Nadu's Only Ganesha Shrine That Worships Him In Human Form


UPI New Rule Explained: Will You Actually Pay To Use UPI Now?

Somewhere on a family WhatsApp group this week, a message is almost certainly doing the rounds claiming UPI is "no longer free." Versions of it have been circulating with different numbers attached, different deadlines, and different degrees of alarm, enough that the confusion has forced the government to issue not one but two separate clarifications within weeks of each other.

That confusion isn't entirely unfounded. The government has, in fact, notified a new UPI charges rule this month, and the National Payments Corporation of India (NPCI) has separately announced a revised fee framework taking effect on October 15, 2026. But the two announcements, taken together, say something far less alarming than the forwards suggest.
What Changed On September 14
On September 14, 2026, the Finance Ministry's Department of Financial Services issued a gazette notification under Section 10A of the Payment and Settlement Systems Act, 2007. The notification does the opposite of what most forwards claimed: it legally protects UPI transactions up to ₹2,000, and all RuPay debit card payments, from any direct or indirect charge by banks or payment system providers.
The confusion traces back further, to August, when Parliament passed the Taxation and Other Laws (Amendment) Bill, 2026, amending the same Section 10A that had previously barred any fee on UPI altogether. That amendment didn't introduce a charge; it simply gave the government legal room to allow one for specific high-value merchant categories in future, while explicitly keeping everyday transfers free.
The Real Change: MDR On Big Merchant Payments, Not On You

The part that actually costs anyone money is a Merchant Discount Rate (MDR), announced by the NPCI and effective October 15, 2026. Crucially, MDR is a merchant-side charge, not something deducted from a customer's account. According to NPCI's own statement, here's what changes:
- Person-to-person (P2P) transfers - sending money to friends, family, or splitting a bill - remain completely free, regardless of amount
- Merchant payments up to ₹2,000 - zero MDR, unaffected, and this covers over 95 percent of all UPI merchant transaction volume
- Merchant payments above ₹2,000 - a 0.4 percent MDR applies, capped at ₹300 per transaction, so even a ₹75,000 purchase attracts no more than ₹300
- Railways, telecom, insurance and fuel payments above ₹2,000 - a flat ₹5 per transaction instead of the percentage rate
- Small merchants receiving up to ₹1 lakh a month via UPI QR - continue to enjoy zero MDR entirely
For context, this 0.4 percent is still far lower than what credit cards typically charge merchants, which is 1.5 to 2.5 percent, or debit cards at up to 0.9 percent.
Will Prices Go Up?
Not directly, and not for most people. The MDR is levied on the merchant, not the customer's UPI app or bank account, and the government has repeatedly clarified that everyday consumers do not pay it. The open question - one even NPCI's own statement hints at - is whether large merchants eventually build that 0.4 percent into shelf prices the way some businesses quietly do with card fees. For now, that remains speculation rather than policy.

 Continue with Google


